Category Archives: News

What Is Short-Term Disability Insurance?

Short term disability insurance pays you when you cannot work because of an injury or illness. Simply stated, you qualify for these benefits when a medical condition prevents you from doing your job. Your plan can probably cover the first months of absence due to sickness or injury. The length of the insurance varies from one policy to another.

If you are ill or injured and cannot work, your short term disability plan can pay a percentage of your usual income defined by the plan. Plans usually cover 60% to 85% of your income, however, certain plans will cover up to 100% of your income.

What Are the First Steps in Applying for Short Term Disability Benefits?

Often, as an injured or ill employee, you will first use any available sick days, which are governed by your employment contract with your employer or your collective agreement. Short term disability insurance is usually the next step after having used all remaining sick days, if available. Once exhausted, then employees are typically entitled to receive long term disability insurance. Many people receive their disability insurance coverage through a plan carried by their employer. It is a good idea to ask about coverage when starting a new job.

What Is the Difference Between Short-Term and Long-Term Disability Insurance?

Like short term disability benefits, long term disability insurance is an insurance that protects employees from loss of income if unable to work. However, certain plans require that the employee apply and get accepted onto short term disability, if they have that coverage, before receiving long term disability.

Quite often, the short term disability benefits will cover the “waiting period” or “elimination period”, which needs to expire before you can qualify for long term disability benefits. In contrast, long term disability typically expires when an employee reaches the age of 65 or retires.

The definition of disability may vary between short term and long term disability. Frequently, short term disability benefits are provided when an employee is unable to do his or her own occupation. Once the employee is approved for long term disability, and 24 months have expired, the definition of disability under the long term disability policy may change in that the employee is entitled to long term disability benefits if they are unable to work in any occupation.

Amount of income received under the policy is another difference between the two types of disability insurance. To determine your entitlement, refer to your benefits schedule in your policy or benefit booklet.

What Is My Disability Coverage as a Canadian Public Servant?

Government of Canada employees are covered by the Treasury Board of Canada’s Disability Insurance Plan. That plan does not include short-term disability coverage. You are expected to be covered by your accumulated sick leave until you meet the thirteen-week minimum waiting period to qualify for long-term disability benefits.

Specifically for those covered by the Treasury Board plan, you are covered for any disability that prevents you from working your regular job for the first 24 months of disability. Afterwards, you will continue to receive benefits if your disability prevents you from working a “commensurate occupation.”

What If I Get Sick and I Do Not Have Coverage?

If you do not have short term disability coverage through your employer or otherwise, you may still qualify for sickness benefits through Employment Insurance (EI). Through EI you may be eligible to receive 15 weeks of EI sickness benefits. There are certain requirements such as having accumulated at least 600 hours of insurable employment during the respective qualifying period.

If your application for short term disability benefits is denied, then you may want to speak an experienced disability benefits lawyer.

We are here to help navigate the short-term disability claim process. Consult one of our experienced Disability lawyers at Raven, Cameron, Ballantyne and Yazbeck LLP if you are considering making a claim for disability benefits or if your disability claim for benefits has been denied.


[This article is for informational purposes only and does not constitute legal advice, which cannot be given without consideration of your individual circumstances.]

By: Raphaëlle Laframboise-Carignan, Anna Lichty and Zachary Rodgers (articling student)

When Does Long Term Disability Begin?

Long Term Disability (LTD) is intended to provide income replacement coverage if you are unable to work due to injury or illness. Long term disability benefits will normally commence once your short term disability benefits, if you have this coverage, have been exhausted. Most Long Term Disability policies contains a waiting period or elimination period, before you can start receiving payments. Once the elimination period passes, the insurance company has to determine whether you are “totally disabled”, i.e. unable to do your job, or in some cases any job, due to an injury or illness. If you meet this definition, which can vary from policy to policy, then your Long Term Disability coverage can begin. The following are some important points you should be aware of when applying for Long Term Disability benefits.

How long is my Elimination Period?

Your insurance policy will provide a specific elimination period, as these vary between insurance companies. In many cases the elimination period is set to correspond with short term benefits. For example, many plans that include short term disability coverage are designed so that your elimination period ends when the short term benefits run out, which means your benefits become payable without a gap in coverage.

How long is the elimination period? Will you be able to access short-term benefits in the meantime? Does your policy say that you have to apply for Employment Insurance benefits? How is your elimination period calculated? These questions would be answered in your policy. Taking the time to read your policy can prevent costly mistakes and loss of time  in the application process.

What is the impact of returning to work on my Elimination Period?

It is very important to understand how your elimination period is calculated. Depending on the method of calculation, you may restart the elimination period if you return to work. This would delay the payment of Long Term Disability benefits. For example, suppose that your policy prescribes a 90 day elimination period. If your policy calculates the period in terms of “consecutive days”, returning to work for just one day during that period  may restart the 90 day waiting period. On the other hand, if your elimination period allows for “interrupted periods”, the you can go to work on certain days without restarting the 90 day process.

If You Have a Recurrent Disability, You May Get to Skip the Elimination Period

If you received Long Term Disability in the past for the same illness or disability, then most Long Term Disability policies contain a clause allowing you to skip the elimination period.  This is usually found in the policy under the heading of “recurrent disability”. The policy will typically treat this later period of disability as a continuation of the earlier period, provided it is within the time limit stated in the policy. For example, suppose you previously went on Long Term Disability with a back injury, and eventually returned to work. If you become disabled later on due to back pain from the same injury, your benefits can be reinstated immediately, without the need to wait for the elimination period to end.

On the one hand, these clauses are useful because they allow you to avoid waiting through another elimination period for the same disability. On the other hand, any time limit for payment of benefits runs from the start of the first period of disability. This means that if your policy pays benefits for two years per claim, the two-year period would not restart the second time you go on Long Term Disability for the same disability. For more information, see our article on Successive Periods of Total Disability.

My Elimination Period is Over and I’m Still Disabled – Do I have to Apply for Long Term Disability?

Receiving short term benefits, if you have this type of coverage, does not automatically entitle you to Long Term Disability coverage even if your disability has not changed. You should start your Long Term Disability application as soon as you know that you are unable to return to work before of illness or injury. At this point, your insurance company will want proof that you are “totally disabled” under the terms of the policy before they approve your claim. The application process can be long and difficult, and it often requires lots of medical evidence. For more information on how to navigate through the Long Term Disability application process, please see our article.

Getting Approved for Long Term Disability – Do I Meet the Definition for “Total Disability”?

Once you have applied for Long Term Disability and your elimination period has passed, the benefits become “payable”, but before you actually get “paid”, the insurance company has to determine that you remain unable to do your occupation. To make this decision, the insurance company looks at the medical documentation and compares it to the definition of “total disability” in your policy. If you meet the definition your Long Term Disability claim will be approved and your benefits will begin.

If there is excessive delay in providing your long term disability benefits, you may have a claim for aggravated (bad faith) and punitive damages against the insurance company. Please see our article “Mental Distress and Punitive Damages in a Long Term Disability Claim”.

Once your benefits begin, they usually continue for 24 months. This 24 month period is called “own occupation” coverage because the insurance company defines total disability as being unable to do the essential duties of your own occupation, whether in your current work place or not.

After 24 months however, the definition of total disability usually changes. If you want to continue receiving benefits you need proof that your disability leaves you unable to perform the duties of any occupation for which you are reasonably qualified. This rule applies even if you are still unable to return to work at your original job. In practice this means that you may lose your benefits even if your medical situation remains unchanged.

Take away

The Long Term Disability application process can be long, complicated and stressful. A Long Term Disability applicant faces a number of legal and administrative hurdles at a time of great vulnerability. It is easy to make mistakes that cause costly delays. An experienced disability lawyer can help you understand the terms of your policy and how to make your way through the application process.

We are here to help navigate the Long Term disability claim process. Consult one of our experienced Disability lawyers at Raven, Cameron, Ballantyne and Yazbeck LLP if you are considering making a claim for disability benefits or if your disability claim for benefits has been denied. 

[This article is for informational purposes only and does not constitute legal advice, which cannot be given without consideration of your individual circumstances.]

By: Raphaelle Laframboise-Carignan, Anna Lichty and Geoff Dunlop (articling student)


Update on Limitation Periods in Long Term Disability Claims

Earlier this year, the Ontario Divisional Court issued a decision in Western Life Assurance Company v. Penttila, 2019 ONSC 14 (CanLII) addressing when the time limit for filing a claim, known as the limitation period, begins to run for individuals who were denied long-term disability (LTD) benefits. The Court determined that the limitation period starts once the individual receives a final decision from the insurance company. This is after all appeals are finished.

Background

Ms. Pentilla was receiving Long Term Disability benefits from Western Life Assurance Company. In February 2013, Western Life advised her that, effective March 2013, she would no longer meet the definition to qualify for benefits. In their letter, Western Life informed her while she could appeal the decision, they were not waiving their right to rely on any statutory time limit. Ms. Pentilla appealed the decision and provided additional medical information. In November 2013, Western life asked for more medical information, and wrote to Ms. Pentilla that they would complete the review of her appeal once they received the information. Their letter did not include any statement about relying on statutory time limits. In October 2014, Western Life wrote to Ms. Pentilla that they had reviewed the new medical information, but their position remained unchanged. Several months later, Ms. Pentilla told Western Life she had not received a decision letter, and so, in June 2015, Western Life wrote to Ms. Pentilla that she did not meet the definition for Long Term Disability benefits and therefore any further benefits remained denied. Approximately one year later, in June 2016, Ms. Pentilla issued her statement of claim.

The Motion Judge’s Decision

Western Life brought a motion for summary judgment that Ms. Pentilla’s claim should be statute barred because she had not brought her claim within two years of it being discovered. In Ontario, the Limitations Act, 2000 provides a two-year limitation period for most claims, meaning that an individual must start legal proceedings within two years of their claim being discovered. The motion judge dismissed Western Life’s motion for summary judgment, finding that Ms. Pentilla’s claim was discovered in October 2014 or June 2015 because before those dates, a reasonable person would not have understood that a proceeding was an appropriate remedy. Western Life appealed that decision to the Divisional Court.

The Divisional Court’s Decision

On appeal, Western Life argued that Ms. Pentilla should have known that a legal proceeding would be an appropriate means to seek a remedy by March 2013, when she no longer qualified for benefits. Ms. Pentilla argued that, by March 2013, Western Life had not finally determined her appeal, so a legal proceeding would not have been appropriate.

The Divisional Court upheld the motion judge’s decision. The court found that the two-year limitation period started on the date it would be appropriate to begin legal proceedings for payment of Long Term Disability benefits that the insurer refused to pay. A reasonable person in Ms. Pentilla’s situation would have made an internal appeal to Western Life before starting legal proceedings. At all times between receiving her initial denial in February 2013 and receiving her final appeal decision in June 2015, Ms. Pentilla believed that Western Life was considering her appeal. In this case, Western Life’s statement that it was not waiving its right to rely on statutory time limits was not sufficiently clear to show Ms. Pentilla that the limitation period was running before her appeal had been decided.

Discussion

The Divisional Court’s decision is a positive step for individuals who have been denied Long Term Disability benefits. It reinforces that the statutory time limit for starting a legal proceeding may not begin to run until the insurance company has issued a final decision. The Court also reinforced that it is reasonable for an individual to go through the insurance company’s internal appeal process before starting litigation.

This decision follows the Ontario Court of Appeal’s decision in Kassburg v. Sun Life Assurance Company of Canada, which found that the court must consider when the claim was clearly and unequivocally denied. In Kassburg, the Court also upheld a motion judge’s conclusion that the insured discovered her claim on the date of the letter in which the insurer told her that her final appeal was denied.

These cases suggest that legal proceedings may be premature until the insurance company’s internal appeal process has run its course. This determination, however, will depend on many factors, including the clarity of the language that the insurance company uses to show that the statutory limitation period runs during the time the internal appeal is being considered. See our article, Limitation Periods for Long-Term Disability Claims. If your insurance company has denied you Long Term Disability benefits, contact a lawyer to discuss your legal rights and how limitation periods may apply in your situation.

[This article is for informational purposes only and does not constitute legal advice, which cannot be given without consideration of your individual circumstances.]

Julia Williams Presented on Careers in Social Justice and Labour Law

On February 28, 2019, Julia Williams participated in a roundtable discussion at the University of Ottawa on careers in social justice and labour law. The roundtable was a Q&A with practitioners offering insight into paths to labour law, followed by a discussion on the challenges and rewards of pursuing a social justice career.  Julia would like to thank the Labour Law and Human Rights Association at the University of Ottawa, Faculty of Law, for inviting her to participate in this event.

RavenLaw Supports the 20th Annual GCTC Lawyer Play Fundraiser

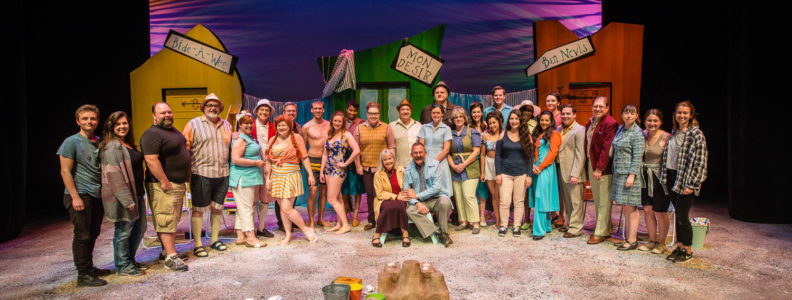
RavenLaw is proud to sponsor the 20th Annual County of Carleton Law Association/Great Canadian Theatre Company Lawyer Play. The annual fundraiser supports the operations of Great Canadian Theatre Company (GCTC) and benefits a charity partner, which this year was St. Mary’s Home, an Ottawa-based social service agency that provides a full range of programs and services for young pregnant women, young moms and dads, and their infants and young children.

Over the last 20 years, the Lawyer Play fundraiser has raised well over $1 million dollars for GCTC and designated charity partners. Each year, the play’s cast is composed entirely of members of Ottawa’s legal community. This year’s play, War of Two Worlds, runs from June 6-8, 2019 and features RavenLaw lawyer Amanda Montague-Reinholdt as Flo.

David Yazbeck Co-chaired Bargaining in the Broader Public Sector Conference

On December 4, 2018, Lancaster House presented its 2018 Bargaining in the Broader Public Sector Conference at the Sheraton Centre Toronto Hotel. The conference tackled current issues facing unions and their members when dealing with collective bargaining in the broader public sector, including such key issues as the role of politics and the Charter at the bargaining table, the changing face of the workforce, and the future of work.

David Yazbeck was pleased to be selected as the union-side co-chair for this conference and to assist in organizing the conference and moderating various panels during the day.

David Yazbeck Appointed to the Board of Directors of COVA-DAAV

RavenLaw is pleased to announce that David Yazbeck has been appointed to the Board of Directors of Copyright Visual Arts – Droits d’outeur Arts visuels (COVA-DAAV). COVA-DAAV is the business operating name of CARCC, which is a copyright collective founded by Canadian Artists’ Representation – Le Front des Artistes Canadiens (CARFAC) in 1990 to assist artists in administering their copyrights. David is also a member of the Board of CARFAC and, as part of the governance structure for COVA-DAAV, CARFAC is entitled to appoint board members to the COVA-DAAV Board.

David is excited for this opportunity to continue his advocacy efforts on behalf of visual artists in Canada, particularly as it relates to protecting and promoting artists’ copyright in Canada and Quebec. Any interested artists from Canada and Quebec may affiliate with Copyright Visual Arts.

Federal Court of Appeal Raises Questions about Reprisal Tribunal Decision

In 2017, the Public Servants Disclosure Protection Tribunal rendered its first decision on the merits of a reprisal complaint under the Public Servants Disclosure Protection Act. As the first decision on the merits, a number of critical issues of legal principle were raised by the parties. Ultimately, the Tribunal ruled on several of these issues, a ruling which had significant implications for future Tribunal cases. In particular, the Tribunal concluded:

  • Intent, in the sense of vengeance, must be proven in order to establish reprisal;
  • Minor or insignificant reprisals were not protected by the Act, effectively imposing a de minimus standard; and
  • An employee cannot receive reprisal protection for subsequent disclosures of the same wrongdoing.

In addition to these legal rulings, the Tribunal dismissed the complaint on the facts, concluding that the employee had not proven that she experienced negative effects as a result of the alleged reprisal measures.

The employee sought judicial review of the Tribunal decision. In a judgment rendered this month, the Federal Court of Appeal dismissed the application, concluding that the Tribunal’s findings that there was no negative effect on the employee could not be set aside.

Counsel had urged the Court to address the legal issues given their impact upon other cases. The Court declined to do so, because this would take it “too far into a law-making role”. In spite of this, the Court went on to comment upon the Tribunal’s analysis as follows:

“But we wish to add that many of the legal conclusions reached by the Tribunal in this case warrant critical scrutiny. As a matter of administrative law, other members of the Tribunal are not bound by the legal conclusions reached here… If the particular case requires it, and until this Court settles the matter, a member of the Tribunal is free to conduct her or his own analysis and reach different legal conclusions.”

By this language, it would appear that the Court has signaled that the reasoning of the Tribunal on these legal issues need not be followed in the future, a conclusion which represents significant progress for complainants who are victims of reprisal.

The employee in this matter was represented by David Yazbeck and Michael Fisher of our firm.

Julia Williams Presents at 2nd Annual OnCALL Conference

On September 29, 2018, Julia Williams was a panelist at the Ontario Region – Canadian Association of Labour Lawyers’ second annual conference (OnCALL2) in Kingston, Ontario. Julia participated in the “Ten Minute Labour Lawyer” panel, presenting on the recent arbitral decision in City of Kingston v CUPE 109. Julia would like to thank the organizers of OnCALL2 for inviting her to participate in this event.


The Critical Importance of Long Term Disability Benefits

Long Term Disability Benefits

Ask most healthy working people to name their greatest financial asset, and more than likely, they will say ‘my house.’ A fair response. After all, maintaining and paying for a home is where a significant chunk of our income and time is spent. 

But for most healthy working people, it’s the wrong answer: A far greater financial asset is their ability to earn an income over the course of their career, often a long period of time. The consequences of not being able to do so can be financially devastating.

Most people have only a hazy understanding of the financial consequences of being unable to continue working due to mental or physical illness. We know that during our working lives, there is always the possibility of being laid off from one job and having to find another, but if chronic illness or a serious accident prevents us from working at all, the option of finding another job disappears. In fact, there are limited options for those employees; one of the options is Long Term Disability (LTD). 

As employment lawyers, we understand that few people think about the possibility of their working lives coming to a premature end. When it does happen, the questions are inevitably many. Here are answers to just a few basic LTD questions:  

How Do You Obtain Long Term Disability Benefits?

Most people who have Long Term Disability benefits have them through their employery, and typically, the cost of these benefits is shared between the employee and the employer. Having the employer pay for some (or all) of the benefits, while superficially attractive, also results in the benefit being taxable. Meaning if you ever receive money under the LTD policy, you will have to pay tax on the amounts you receive.

If, on the other hand, you pay for the full cost of the LTD policy, any money received would be non-taxable. Having a non-taxable benefit can make a huge difference in the event you need to rely on LTD benefits, as you are often receiving only a portion of your prior income and may be struggling to live off significantly reduced income. 

It is important to explore with your employer or your union whether your salary can be increased by the value of the employer contribution, and then you can make the full payment for the  LTD policy.

Another option is to buy full LTD insurance yourself if your employer does not offer this benefit as part of your remuneration package. 

Do You Have Sufficient Long Term Disability Benefits?

The answer to this question will depend on a variety of factors, including age, savings, cost of benefits, number of dependents, etc. It is also probable that the answer will change over time as your personal circumstances change. Given the importance of the benefit, should you be unable to work, it is important to seek advice from an LTD insurance expert.

What Happens To Your Long Term Disability Benefit If You Lose Your Job?

It is extremely common for people to lose their LTD benefits shortly after they lose their jobs. Termination letters typically contain provisions ending Long Term Disability benefits after the statutory notice period found in the Employment Standards Act. This period is often a matter of weeks rather than months.

After this period, former employees are frequently left with no LTD benefits while they look for other work. Insurers will often not sell LTD insurance to the unemployed, and that compounds an already stressful situation.

One way to avoid this scenario is to purchase LTD insurance independently. (See next question).   

How Can You Protect Yourself, such that Long Term Disability Benefits Are Not Lost?

One method of ensuring LTD protection in the face of uncertain job security is to have your own LTD benefits policy that you have arranged for outside of your employer. That way, should you lose your job, your coverage continues. This type of arrangement will be particularly important for those with precarious employment.

Own Occupation Disability Insurance – The Gold Standard, but what is it?

Most LTD policies provide for “own occupation” disability insurance coverage for a period of two years. This means that should you be unable to perform the essential functions of your own job, you would meet the definition of disability and should receive benefits.

After that initial period (usually two years), in most insurance policies, the coverage definition changes to “any occupation.” This means that even if you continue to be unable to complete the essential functions of your own job, say as a teacher, if you can do any work, you may no longer be entitled to benefits. If this other occupation is something for which the employee is suitable by reason of their background, the insurer can insist they take the job or risk having their benefits cut off.

It is possible to independently purchase “own occupation” disability insurance coverage at an increased cost. This will provide you with LTD benefits, should you be unable to perform the essential duties of your own occupation. It will typically last until age 65.

[This article is for informational purposes only and does not constitute legal advice, which cannot be given without consideration of your individual circumstances.]